Can You Assume a 3.25% FHA Mortgage? A Minneapolis Condo Example
When people talk about buying a home, most assume they'll need to take out a brand-new mortgage at whatever interest rates are available today. But there's another possibility that doesn't get nearly as much attention: assuming the seller's existing mortgage.
I'm currently representing a condominium at Summit House in Minneapolis where the seller has an existing FHA mortgage with a 3.25% interest rate. And importantly, Rocket Mortgage has verbally confirmed to the seller that the loan is assumable by a qualified buyer.
With mortgage rates substantially higher than 3.25% in recent years, it's worth taking a closer look at how an assumable mortgage works, what a buyer might save, how much cash would be needed, and what the approval process actually involves.
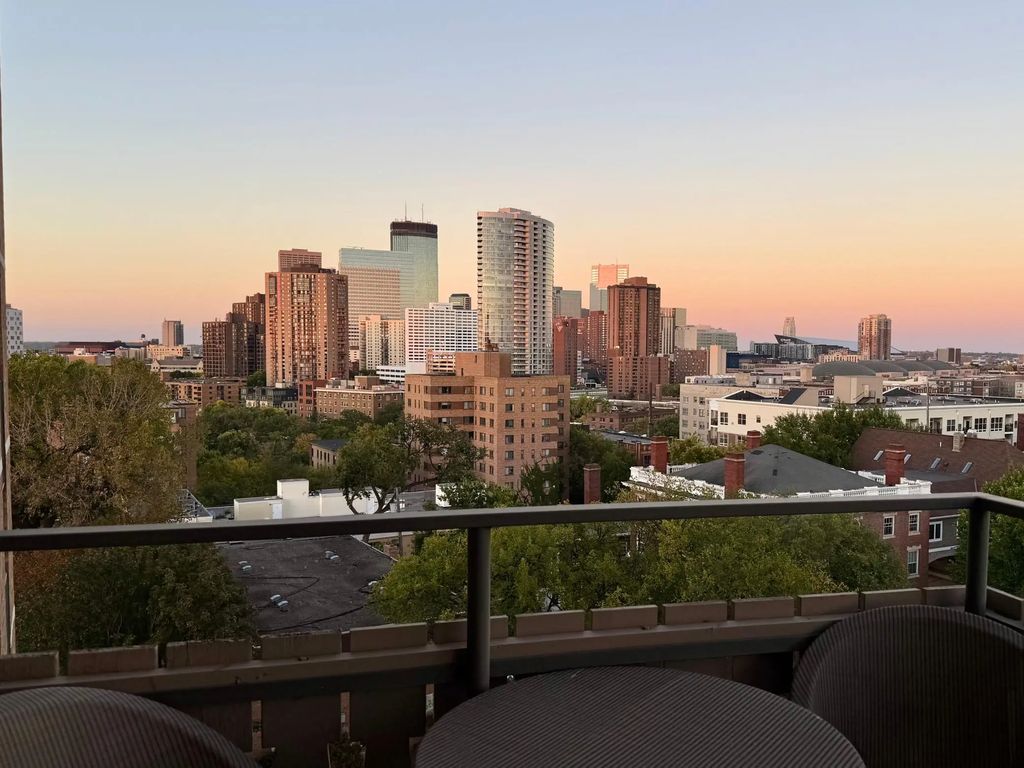
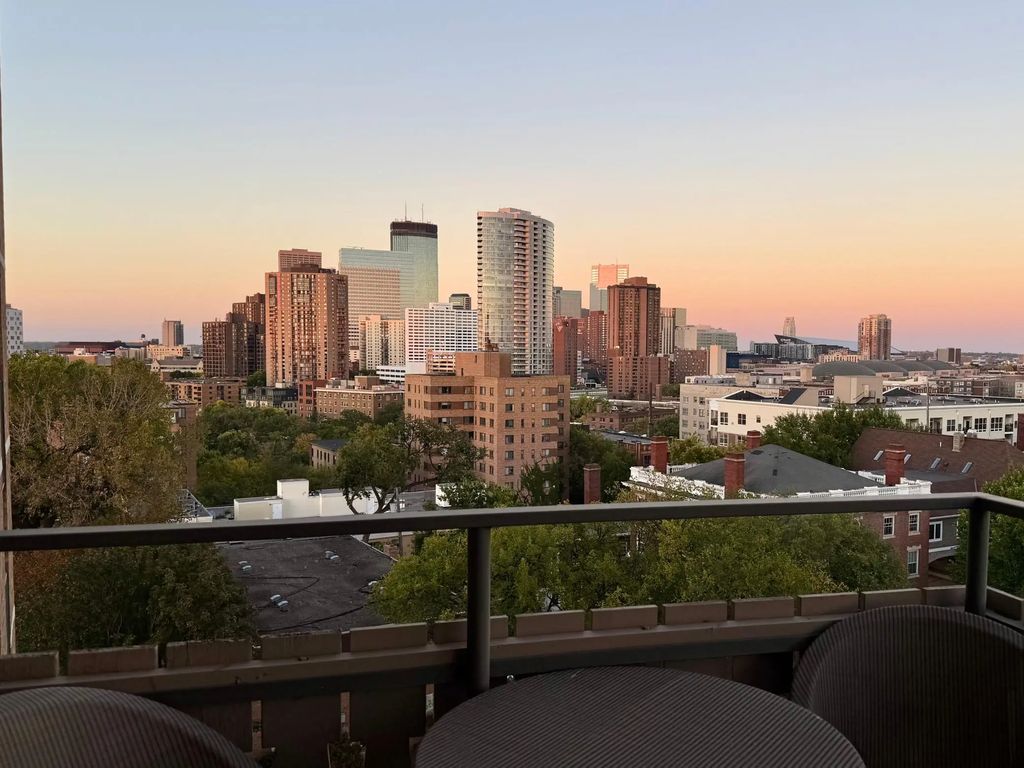
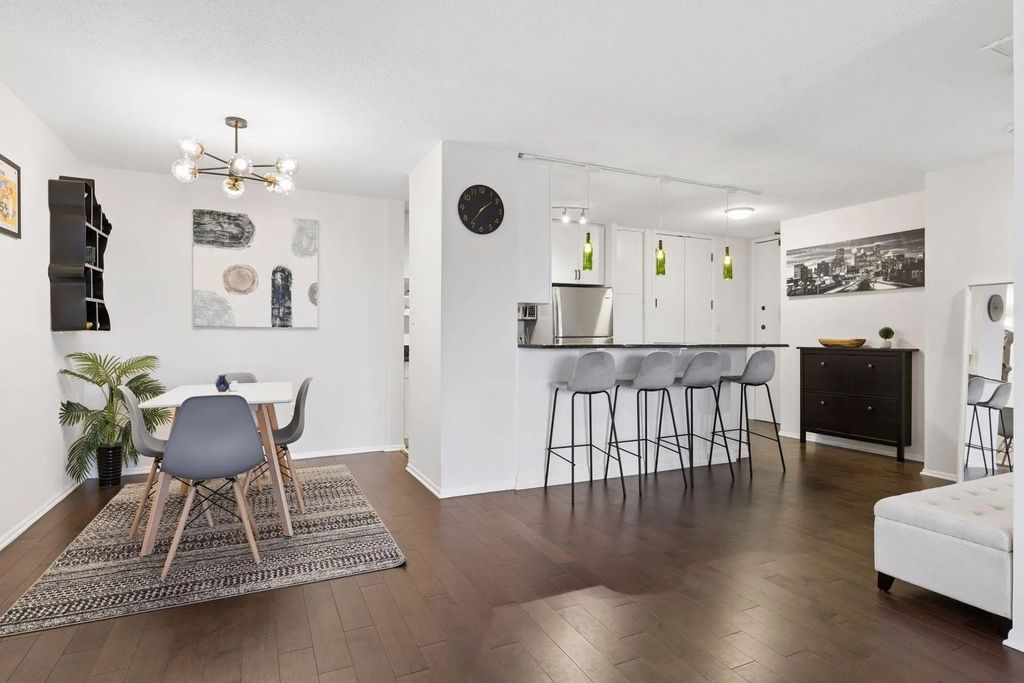
The property is 400 Groveland Avenue #914, Minneapolis, currently offered at $129,900.
Financing opportunity: According to the seller's conversation with Rocket Mortgage, the existing 3.25% FHA loan is assumable, subject to the buyer qualifying and completing Rocket's approval process. The assumption has not yet been approved for a specific purchaser, and additional fees, escrow funding, and closing requirements apply.
What Is an Assumable Mortgage?
An assumable mortgage allows a qualified buyer to take over a seller's existing home loan instead of replacing it with an entirely new mortgage.
That can include the existing interest rate, outstanding principal balance, and remaining repayment schedule. If the seller secured a low interest rate several years ago, the ability to assume that loan may have considerable value to a buyer.
But an assumption isn't automatic. The buyer generally must qualify with the mortgage servicer, complete the required approval process, and arrange for any additional funds needed to purchase the property.
Which Types of Mortgages Can Be Assumed?
Not every mortgage can be assumed. The loan program and specific mortgage terms matter.
- FHA loans: Generally assumable, subject to applicable FHA rules, buyer qualification, and servicer approval.
- VA loans: Generally assumable with approval. Additional considerations include the seller's VA entitlement and release of liability.
- USDA loans: Certain USDA mortgages may be assumed, but the applicable program rules, approval requirements, and interest-rate treatment must be verified.
- Conventional loans: Most modern conventional mortgages contain due-on-sale provisions that generally prevent an ordinary buyer from simply taking over the existing loan. Certain exceptions or special circumstances may apply.
For this particular property, we're discussing an existing FHA-insured mortgage.
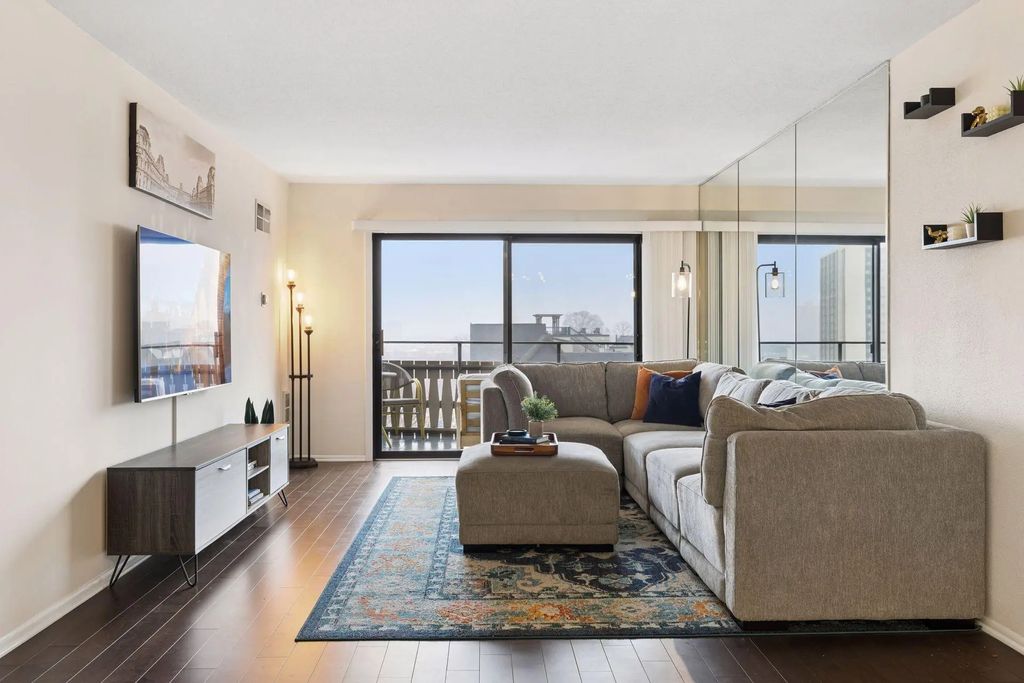
A Real Example: Summit House #914 in Minneapolis
Let's look at the actual numbers from the seller's October 2026 mortgage statement and the information subsequently confirmed with Rocket Mortgage.
| Property and Mortgage Details | Amount |
|---|---|
| Asking price | $129,900 |
| Existing FHA loan balance | $123,168.58 |
| Existing interest rate | 3.25% |
| Original loan term | 30 years |
| Original closing date | June 29, 2021 |
| Remaining loan term | 24 years, 9 months |
| Current principal and interest | $619.62/month |
| Loan assumption status | Verbally confirmed assumable by Rocket Mortgage, subject to buyer approval |
Rocket Mortgage has confirmed to the seller that the existing loan can be assumed by a qualified purchaser. The buyer must complete Rocket's application, underwriting, and approval process.
The interest rate and loan balance shown above relate to the existing mortgage. The outstanding principal balance will change as regular mortgage payments are made.
How Much Cash Would a Buyer Need to Assume the Loan?
This is one of the most important parts of an assumable mortgage.
A buyer doesn't automatically get to purchase the property with no down payment just because they're taking over an existing loan.
Instead, the buyer generally needs to pay the difference between the agreed purchase price and the mortgage balance being assumed.
| Purchase Calculation | Amount |
|---|---|
| Purchase price | $129,900.00 |
| Existing mortgage balance | $123,168.58 |
| Estimated buyer cash toward purchase | $6,731.42 |
In this example, that difference is approximately 5.2% of the purchase price.
This isn't a new FHA loan with a standard 3.5% down payment. It's the amount of cash needed to bridge the difference between the purchase price and the existing mortgage balance.
What Additional Costs Should a Buyer Expect?
According to the seller's conversation with Rocket Mortgage, the assumption involves a one-time basic fee of up to $1,800.
Rocket also indicated that the buyer will need to fund a new escrow account because the seller's existing escrow balance will be returned to the seller.
The required escrow deposit will depend on the servicer's calculations, including applicable property taxes, insurance, and other required adjustments.
Other closing costs, recording charges, or county-related fees may also apply.
At the current asking price, the estimated $6,731 difference between the purchase price and the existing mortgage balance is therefore only part of the buyer's total cash needed. The buyer should also plan for the assumption fee, escrow funding, prepaid expenses, and other applicable closing costs.
Rocket Mortgage will determine the final requirements and amounts during the assumption process.
What Would the Monthly Payment Look Like?
The seller's existing mortgage statement provides a useful starting point for understanding the monthly housing expense.
| Existing FHA Mortgage and Housing Expense | Monthly |
|---|---|
| Principal and interest at 3.25% | $619.62 |
| Property tax escrow | $396.20 |
| Insurance escrow | $59.41 |
| FHA mortgage insurance | $89.74 |
| Mortgage payment including escrow | $1,164.97 |
| HOA dues | $932.00 |
| Total current monthly expense | $2,096.97 |
These are the seller's current mortgage payment components plus the stated association dues, not a guaranteed payment for a future buyer. Property taxes, escrow deposits, insurance, and other charges can change after a purchase or loan assumption.
What Do the $932 Monthly HOA Dues Include?
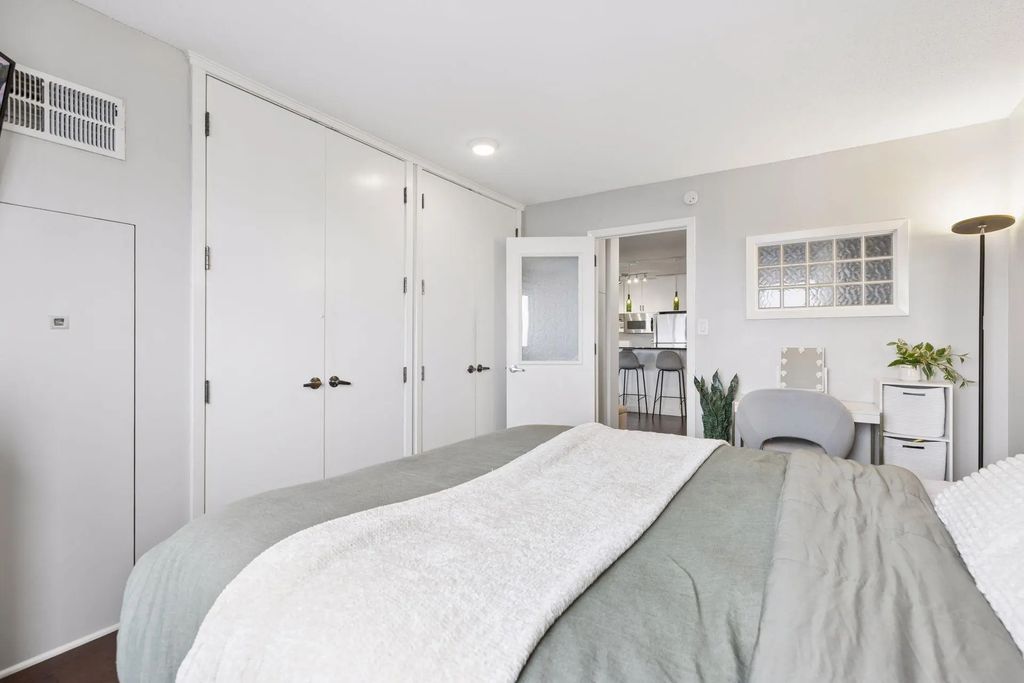
One important detail about this particular condo is that all utilities are included in the monthly HOA dues, including electricity, cable television, and internet service.
That makes the $932 monthly association fee more meaningful when evaluating the property's overall cost of ownership. Rather than paying separately for electricity, cable TV, internet, and other included utilities, those expenses are already incorporated into the association dues.
It's an important distinction when comparing Summit House with other Minneapolis condominium buildings where some or all of these services may be billed separately.
The property also benefits from updated mechanical systems, another consideration for buyers evaluating the building's condition and ongoing maintenance needs.
Association dues remain a substantial part of the total monthly expense, but understanding what's included provides a more complete picture of the actual housing costs.
How Does That Compare With a New Conventional Mortgage?
Now let's compare the existing FHA mortgage with a hypothetical new 30-year conventional mortgage using a 3% down payment.
For illustration, we'll use a 7.55% conventional interest rate. This is a comparison assumption, not a lender quote or a guarantee that this particular condominium qualifies for 3%-down conventional financing.
| Financing Comparison | Existing FHA Assumption | New Conventional Loan |
|---|---|---|
| Purchase price | $129,900 | $129,900 |
| Cash toward purchase | Approx. $6,731 | $3,897 |
| Mortgage principal | Approx. $123,169 | $126,003 |
| Interest rate | 3.25% | 7.55% illustrative |
| Repayment term | 24 years, 9 months remaining | New 30-year term |
| Principal and interest | $619.62 | Approx. $885 |
| Mortgage insurance | $89.74 currently | Estimated $65 PMI |
| Property taxes | $396.20 | $396.20 |
| Insurance | $59.41 | $59.41 |
| HOA dues | $932 | $932 |
| Estimated total monthly | $2,096.97 | Approx. $2,338 |
Under these assumptions, the existing FHA mortgage could reduce the estimated monthly housing expense by approximately $240 compared with the conventional example, or roughly $2,900 over the first year.
Importantly, both scenarios include the same $932 HOA dues, which cover utilities including electricity, cable TV, and internet. Those included services should be considered when comparing this property's monthly expenses with other condominium options.
However, the conventional buyer would initially contribute less cash toward the purchase price in this example, and the conventional loan would begin a new 30-year repayment schedule. The existing FHA loan has a shorter remaining term.
The conventional scenario assumes the buyer qualifies for a 3%-down program and the condominium satisfies the lender's project requirements. Actual interest rates, mortgage insurance premiums, and cash-to-close figures depend on the buyer and lender. Both scenarios exclude special assessments and other costs not specifically identified.
Does the Condo Building Need to Be FHA Approved?
This is an especially important question for condominium buyers.
FHA approval requirements for obtaining a new FHA-insured mortgage on a condominium are not necessarily the same as the requirements for assuming an FHA mortgage that already exists.
The seller specifically asked Rocket Mortgage whether Summit House's current lack of FHA approval would prevent a buyer from assuming the existing loan.
According to the seller, Rocket's representative indicated that they do not anticipate an issue because the buyer would be assuming an existing FHA-insured mortgage rather than originating a new FHA loan.
That's an encouraging distinction. An existing FHA mortgage may be eligible for assumption even when a condominium building is no longer approved for new FHA financing.
However, the representative's comments were preliminary. The specific transaction will still need to satisfy Rocket Mortgage's requirements and any applicable condominium association rules.
The important takeaway is that Rocket Mortgage has verbally confirmed the loan is assumable and does not currently anticipate the building's FHA approval status preventing an otherwise qualified buyer from proceeding.
How Does the FHA Mortgage Assumption Process Work?
Rocket Mortgage has provided the seller with additional information about how the assumption process would work for this particular condo.
Step 1: The Property Goes Under Contract
Once a purchase agreement is in place, the buyer's information is submitted to Rocket Mortgage to begin the assumption process.
Step 2: Rocket Mortgage Reviews the Buyer
The buyer must qualify for the existing loan. Rocket will provide a list of required documentation and tasks, which may include income verification, credit review, financial information, and other underwriting requirements.
Step 3: The Buyer Completes the Required Documentation
Rocket indicated that the buyer's responsiveness can significantly affect the timeline. Completing requested items promptly may help prevent avoidable delays.
Step 4: Rocket Reviews and Approves the Assumption
The buyer must meet the applicable qualification and loan requirements. The existing interest rate does not eliminate the need for approval.
Step 5: The Transaction Is Scheduled for Closing
According to the seller's conversation with Rocket, an assumption typically takes approximately 90 days to close, although the actual timeline can vary.
Why Closing Dates Require Extra Planning
Rocket Mortgage also advised that assumption closings for this loan can occur only during the first two weeks of a month.
That restriction can create additional scheduling challenges. If the transaction is not ready within the permitted closing window, the parties may need to wait until the following month, potentially adding additional time to the process.
For buyers and sellers, this means the purchase agreement should allow adequate time for assumption approval and closing coordination.
A mortgage assumption can offer attractive financing terms, but it generally requires more patience and flexibility than a typical purchase financed with a new mortgage.
What Are the Potential Drawbacks of an Assumable Mortgage?
- Cash needed: The buyer must cover the difference between the purchase price and the assumed loan balance, along with applicable transaction expenses.
- Qualification: Rocket Mortgage must approve the buyer and assumption.
- Remaining term: The buyer takes over the existing 24-year-and-9-month repayment schedule rather than receiving a new 30-year term.
- Mortgage insurance: Existing FHA mortgage insurance obligations may continue and should be reviewed.
- Closing timeline: Rocket Mortgage indicates that assumptions typically take approximately 90 days and are subject to specific monthly closing windows.
- Condominium considerations: Association financials, insurance, project eligibility, and lender requirements still matter.
The seller should also obtain confirmation of a formal release of liability as part of the approved assumption process.
When Does Assuming a Mortgage Make Sense?
In my opinion, an assumable mortgage is worth exploring when the seller has an interest rate materially below the rates available for new financing and the buyer has enough funds to cover the equity difference.
The opportunity can become particularly interesting when the outstanding loan balance is close to the purchase price, as it is in this Summit House example.
But I would never evaluate a condominium solely on its mortgage interest rate. Association dues, reserves, building maintenance, potential assessments, insurance, resale considerations, and the overall cost of ownership remain just as important.
In this particular case, the combination of an existing 3.25% FHA mortgage, updated mechanical systems, and HOA dues that include all utilities gives buyers several factors to evaluate beyond the asking price alone.
A low interest rate can be a valuable financing feature, but the property still has to make sense for the buyer.
Interested in Summit House #914 or Other Minneapolis Condos?
400 Groveland Avenue #914 is currently offered at $129,900 and has an existing FHA mortgage at 3.25%.
Rocket Mortgage has verbally confirmed to the seller that the loan is assumable by a qualified buyer, subject to completing the lender's application and approval process.
The current mortgage balance is approximately $123,169, with 24 years and 9 months remaining. The buyer would need to cover the difference between the purchase price and the assumed loan balance, along with applicable assumption fees, escrow funding, and closing costs.
Buyers should also plan for an assumption process that Rocket indicates typically takes around 90 days, with specific closing-date restrictions.
Beyond the financing, the condo offers updated mechanical systems and monthly HOA dues that include electricity, cable TV, internet, and other utilities.
I've spent more than two decades working with Minneapolis condominiums, and financing is only one part of evaluating a building and an individual unit.
Explore the Minneapolis Condo & Loft Guide, or contact me if you'd like to discuss Summit House, assumable mortgages, or other condo options around Downtown Minneapolis.
Financing illustration prepared October 2026. Loan assumption information is based on the seller's conversation with Rocket Mortgage. Assumability has been verbally confirmed, but individual buyer approval and final transaction terms remain subject to Rocket Mortgage's requirements. Rates, loan balances, mortgage insurance, taxes, HOA dues, and lender requirements may change. Consult a qualified mortgage professional and the existing loan servicer for property-specific financing terms.
Enjoy this blog post? Click here to subscribe for updates
Leave A Comment